on SAPARDIS S.A. (ETR:PUM)
PUMA's Q3 2026 Sales Performance & Outlook
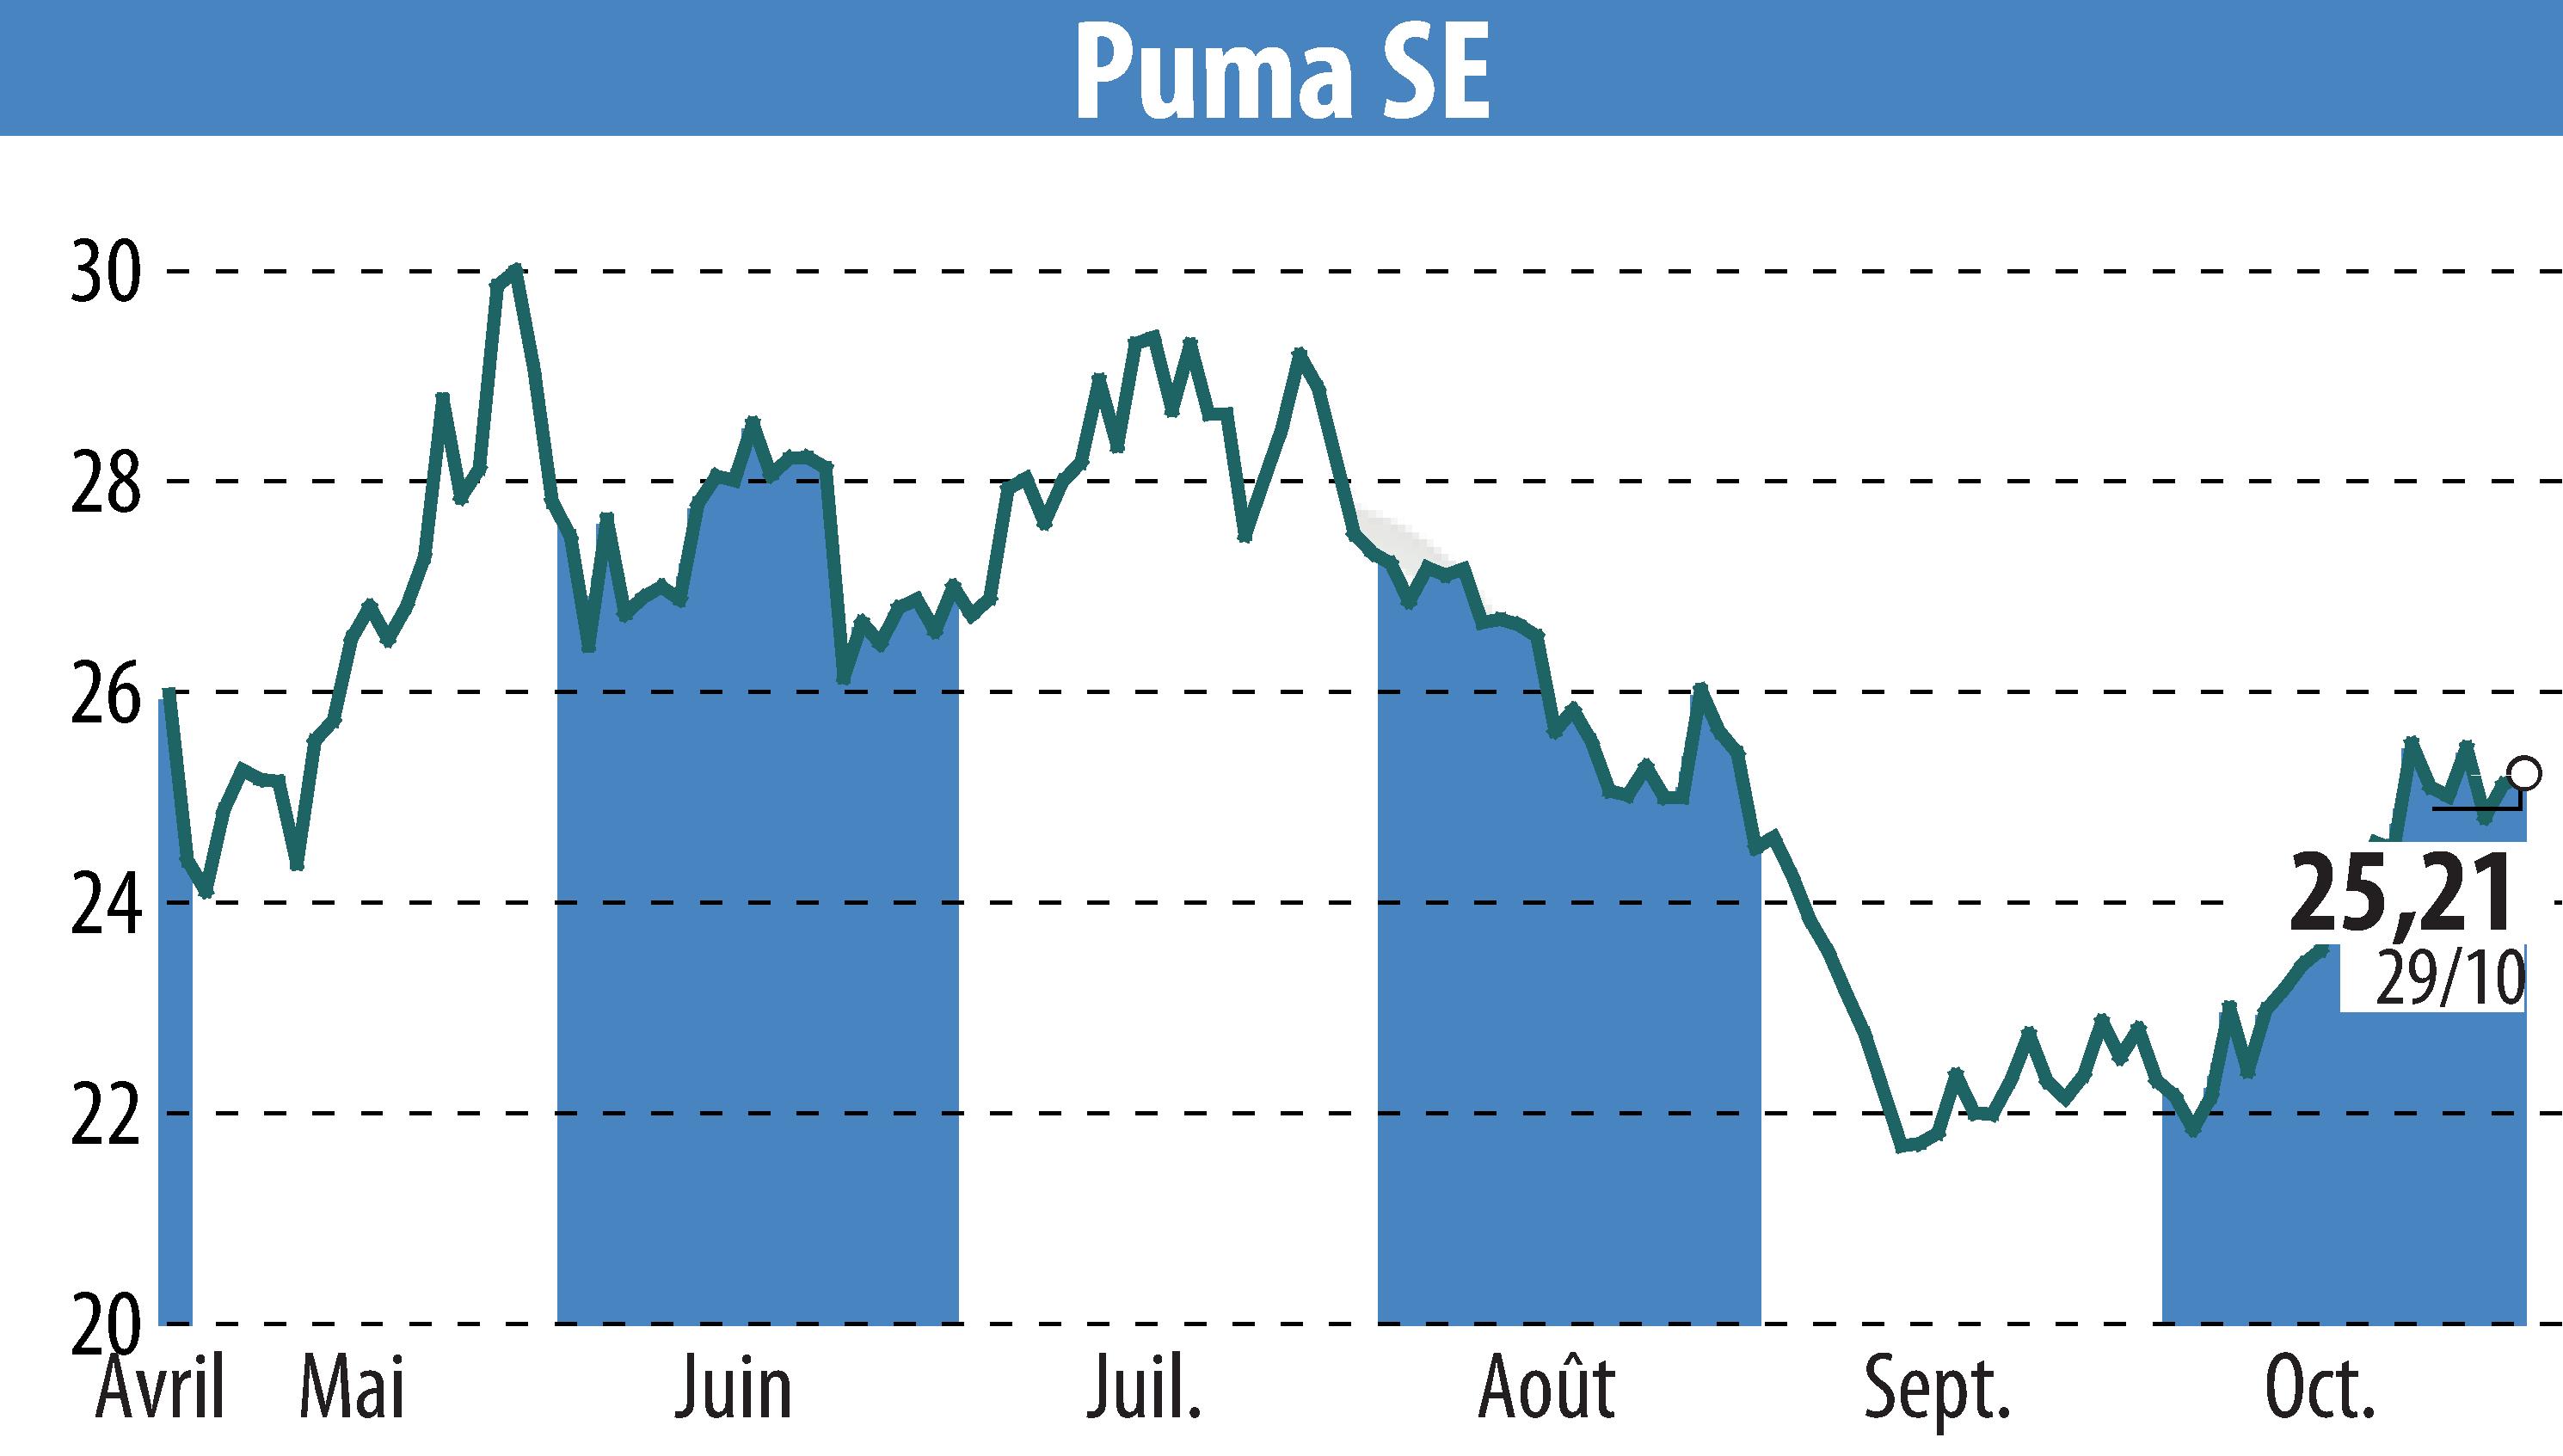
In Q3 2026, PUMA reported a 6.3% currency adjusted sales decline to €1,776.2 million, attributed to reset measures and weaker demand, especially in North America and EMEA. Despite a challenging sales landscape, the gross profit margin improved by 420 basis points to 49.5%, mainly due to lower sourcing prices and positive currency impacts. Nevertheless, the company's EBIT fell to €-11.4 million.
While sales dipped in the Americas and EMEA regions, growth was recorded in Asia/Pacific by 10%. The brand's direct-to-consumer business saw a slight increase, despite a decrease in sales from owned stores. PUMA tightened its FY 2026 EBIT outlook to a range of €-80 million to €-130 million and revised CAPEX expectations.
ANTA Sports becoming PUMA's largest shareholder was a highlight, marking a significant strategic development for future growth.
R. P.
Copyright © 2026 FinanzWire, all reproduction and representation rights reserved.
Disclaimer: although drawn from the best sources, the information and analyzes disseminated by FinanzWire are provided for informational purposes only and in no way constitute an incentive to take a position on the financial markets.
Click here to consult the press release on which this article is based
See all SAPARDIS S.A. news